Implied vs realized volatility
Realized volatility is how much a stock actually moved and implied volatility is how much option prices assume it will move, and comparing the two is the core question of a volatility desk.
- 5 min
- 3 questions
- Lesson 4 of 5
Why you would care
Are options cheap or expensive for how this stock really moves? Two traders look at the same option. One says "expensive", the other "cheap". Usually they are comparing it with different things. Volatility is the price of an option in disguise. Once you can turn it into a daily move in dollars, you can judge it yourself.
The idea from scratch
Realized volatility: what happened
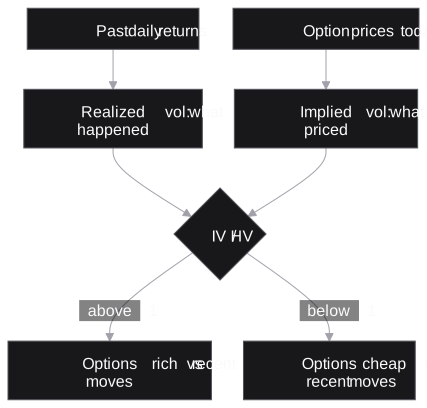
Take a stock's daily returns (the percentage change each day). Realized volatility (also historical volatility, HV) is how spread out they are: their standard deviation, scaled to a year.
The rule of 16 works both ways: daily move ≈ yearly volatility / 16. A 32% volatility means about 2% a day.
Implied volatility: what is priced in
An option's price depends on how much the stock is expected to move (The Greeks in plain words: vega). Turn the formula around: given the option's market price, which volatility makes the formula give that price? That number is the implied volatility (IV). It is the market's forecast, expressed as a yearly volatility.
Expected move
IV turns into a dollar range: expected move ≈ price x IV x √(days / 365).
IV against HV
| Situation | Reading |
|---|---|
| IV above HV | Options price more movement than recently seen: "rich" (often normal, before events) |
| IV below HV | Options price less movement than recently seen: "cheap" |
Most of the time IV sits a little above realized volatility: option sellers ask a premium for taking the risk. That gap is the volatility risk premium, and a vol desk lives on it.
See it in Gloom
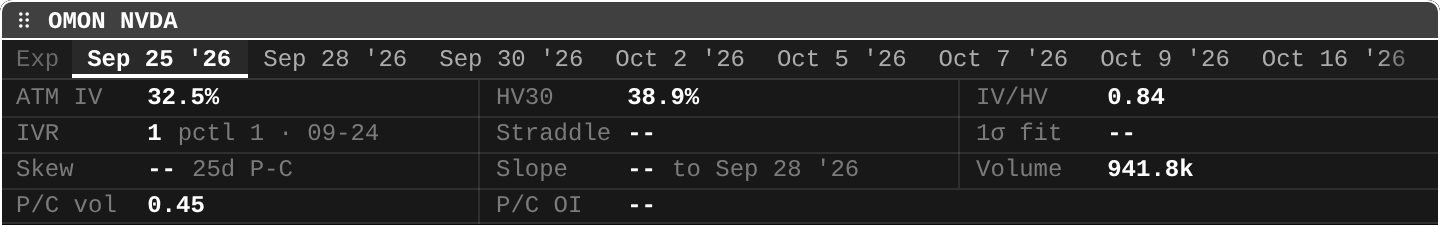
open ittype OMON NVDA; the strip sits above the chain.
ATM IV 32.5%: the implied volatility of the at-the-money options for this expiry.HV30 38.9%: realized volatility over the last 30 days.IV/HV 0.84: implied is below realized. Options priced less movement than NVIDIA had just shown.IVR 1 pctl 1 · 09-24: IV rank and percentile: implied vol is near the lowest level of its past year (taught in IV history and rich or cheap).- Rule of 16: 32.5% / 16 ≈ 2% a day; 38.9% / 16 ≈ 2.4% a day.
Practice and recap
Try it3 tasks
- A stock with 48% implied vol: about how much a day? (48 / 16 = 3%.)
- Stock at 200, IV 20%, 91 days: expected move? (200 x 0.20 x √0.25 = 200 x 0.20 x 0.5 = 20 dollars.)
- In the strip, would an option seller like or dislike IV/HV 0.84? (Dislike: they are paid less than recent movement suggests.)
Common mistakes4 mistakes
- Comparing an IV for one expiry with an HV over a different window.
- Thinking IV forecasts direction. It is size only.
- Forgetting events: IV jumps before earnings and falls right after (the "vol crush").
- Reading "cheap" as "will go up". IV can stay low.
Check yourself3 questions
- What is realized volatility?
- How do you get a daily move from a yearly volatility?
- Why is IV usually a bit above realized volatility?
Answers
- How much a stock actually moved: the standard deviation of its daily returns, scaled to a year.
- Divide by about 16 (the square root of 252 trading days).
- Option sellers ask a premium for carrying the risk of big moves: the volatility risk premium.
Words in this lesson7 words
- realized (historical) volatility, HV
- How much a price actually moved, as a yearly %.
- implied volatility, IV
- The volatility today's option prices assume.
- rule of 16
- Daily move ≈ yearly volatility / 16.
- expected move
- Price x IV x √(days/365): the typical range options price.
- IV/HV
- Implied over realized: above 1 rich, below 1 cheap.
- volatility risk premium
- The usual gap of IV over realized vol, earned by option sellers.
- vol crush
- The drop in implied volatility right after an expected event.
Educational material about reading market data, not investment advice.