Screening option trades (CSP)
CSP builds the same option trade on a list of stocks at once (a cash-secured put, a covered call, a spread, a condor, a straddle, a strangle or a calendar) and ranks them, so you can see which name pays most for the risk.
- 6 min
- 3 questions
- Lesson 3 of 3
Why you would care
You want to sell a put on a stock you would not mind owning. JPM, KO or XOM: which pays most for the same kind of put? Building it in
OSAfive times is slow.CSPpicks the contracts the same way on every name and puts them in one table.
The idea from scratch
The cash-secured put
You sell a put and keep enough cash to buy the shares at the strike. If the stock ends below the strike at expiry, you can be assigned: made to buy 100 shares per contract at the strike. If it ends above, you keep the premium.
CSP takes the expiry nearest 30 days out and the put whose delta is nearest 0.30 (a rough market guess of a 30% chance of ending in the money). It ranks by the yield at the bid: a seller usually gets the bid, so a name that only looks rich at the midpoint does not win.
Other trades, same screen
| Tab | The trade |
|---|---|
| Covered call | Own 100 shares, sell a call above the price |
| Vertical | Sell one option and buy one further out on the same expiry (bull put, bear call), or the reverse (bull call, bear put) |
| Iron condor | A bull put spread below the price plus a bear call spread above it |
| Straddle | A put and a call at the strike nearest the price, both sold or both bought |
| Strangle | A put below and a call above the price, both sold or both bought |
| Calendar | Sell a call, buy the same strike about 30 days later |
A trade that takes money in opens for a credit; one that costs money, for a debit. The bought options further out are the wings: they cap the loss.
Each row gives the max gain, the max loss (unlimited where nothing caps it), the break-evens and the probability of profit (PoP): a pricing model's chance that the trade is in profit when its first option expires, at today's implied volatility. A model's figure, not a forecast. Then the ranking:
Credit trades
the return a year, max gain / max loss, annualized.
Debit verticals and calendars
the reward to risk, max gain / max loss (
2.68x).Straddles and strangles
IV rank, highest first to sell, lowest first to buy.
See it in Gloom
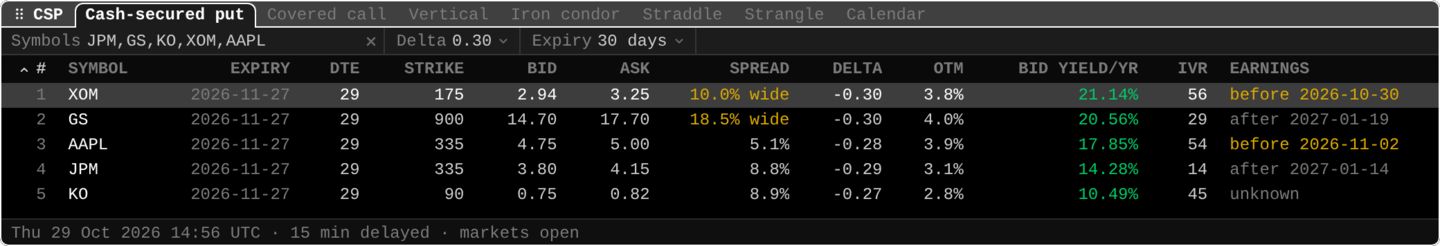
Open ittype CSP JPM, GS, KO. The tabs on top pick the strategy, the bar picks the delta and the expiry, and Enter opens the selected trade in OSA.
XOM ... 175 ... 21.14%: the 175 put, 3.8% below the price, pays 21.14% a year at the bid. It ranks first.10.0% wide: the bid-ask spread is over 10% of the mid. Still ranked, but flagged: you may not get that price.before 2026-10-30: earnings come before expiry, so the stock can jump through your strike.afterwith a date is the reverse;unknownmeans no date is published, andunavailablethat the earnings calendar could not be read this time, so checkERNyourself.
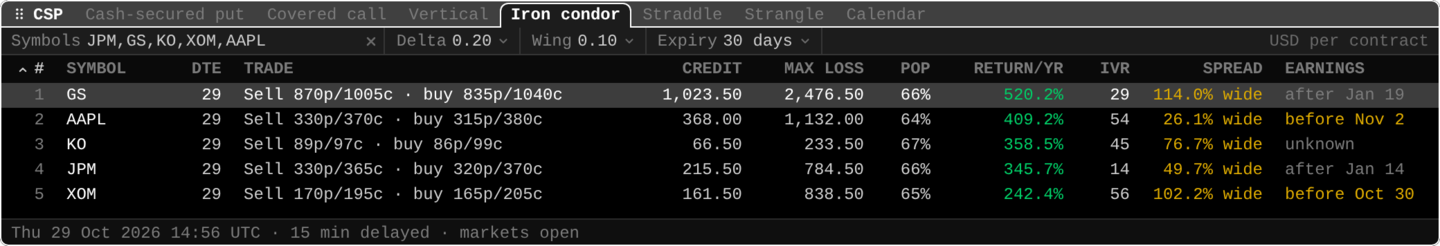
KO Sell 89p/97c · buy 86p/99c: sell the 89 put and the 97 call, buy the 86 put and the 99 call.66.50 233.50 67%: you collect 66.50 dollars, can lose at most 233.50, and the model gives a 67% chance of profit.358.5%: 66.50 / 233.50 is 28.5% in 29 days, scaled to a year. Every spread here is flagged wide, so the real credit would be smaller.
Practice and recap
Try it3 tasks
- A 50 put sold for 0.80, 30 days out: yield on cash? (80 / 5,000 = 1.6%; about 19.5% a year.)
- KO's condor takes in 0.665 a share. Where is its upside break-even? (97 + 0.665 ≈ 97.67.)
- Why rank puts at the bid? (A seller usually fills at the bid; the mid flatters wide markets.)
Common mistakes4 mistakes
- Reading a high annualized yield as a safe return. It pays you for the risk of owning the stock lower down.
- Ignoring the
wideflag: the prices may not be fillable. - Selling premium just before earnings without noticing the flag.
- Treating PoP as a promise.
Check yourself3 questions
- What does "cash-secured" mean?
- Which trades are ranked by reward to risk?
- What caps the loss of an iron condor?
Answers
- You keep enough cash to buy the shares at the strike if you are assigned.
- Debit verticals (bull call, bear put) and calendars.
- Its wings: the put bought below and the call bought above.
Words in this lesson11 words
- cash-secured put
- Selling a put while holding the cash to buy the shares at the strike.
- assignment
- Being made to buy (or sell) the shares at the strike when an option you sold is exercised.
- annualized yield
- A premium as a share of the cash, scaled to a year.
- credit / debit
- Money a trade takes in / costs when you open it.
- vertical spread
- One option sold and one bought on the same expiry at different strikes.
- iron condor
- A bull put spread and a bear call spread together.
- strangle
- A put and a call at different strikes, both bought or both sold.
- calendar spread
- Sell an option and buy the same strike on a later expiry.
- wing
- A bought option further out that caps a spread's loss.
- probability of profit (PoP)
- A model's chance that a trade ends in profit.
- reward to risk
- Max gain divided by max loss.
Educational material about reading market data, not investment advice.